The essential takeaway: Negative gearing prioritizes long-term capital growth through tax deductions on losses, suiting high-income earners with sufficient cash reserves. Positive cashflow delivers immediate taxable income , ideal for risk-averse investors in high-yield markets like Gladstone.
Example: a 7.05% yield in regional QLD generates $12,000/year profit, while tax deductions cut a $9,000 loss to $6,000 . Your decision depends on income, risk, and local market dynamics.
This article was first published on 19 January 2026 and updated on 14 October 2026 for the Federal Budget changes to negative gearing and capital gains tax, and for current Gladstone figures. Rates and market data change without notice, so confirm current figures before you rely on them.
Update, 14 October 2026: negative gearing is changing
The 2026-27 Federal Budget, handed down on 12 May 2026, limits negative gearing to new builds from 1 July 2027. The measure became law through the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, which received Royal Assent on 26 June 2026.
According to the Budget papers, existing arrangements stay unchanged for all properties held before Budget night. Investors who buy established housing after Budget night can still deduct losses against residential property income and carry unused losses forward, but cannot deduct them against other income such as wages. Investors who buy new builds can still deduct losses from other income.
The 50% capital gains tax discount is also replaced from 1 July 2027, with a discount based on inflation and a minimum 30% tax on gains. The change applies only to gains arising after 1 July 2027, and investors in new builds can choose the 50% discount or the new arrangements.
Why this matters for the comparison below: for an established home bought after Budget night, the tax saving that makes a negatively geared property easier to carry, deducting the shortfall against your salary, is not available from 1 July 2027. That puts more weight on cashflow and on capital growth carrying the property by themselves. Opteon reports that investors made up around 60% of Gladstone residential purchases over the previous four years and that sales slowed after the announcement.
This is general information, not tax advice. Speak to an accountant or tax adviser about how the changes apply to you before you buy.
Struggling to decide between negative gearing Queensland strategies and pursuing positive cashflow? You’re not alone. This guide demystifies both approaches, revealing how Gladstone’s property market, where industrial demand supports rental yields above 5% in some suburbs, can tilt your decision. Learn whether prioritizing tax deductions through short-term losses (negative gearing) or securing immediate income (positive cashflow) aligns with your risk appetite, income stability, and long-term wealth goals.
We’ll unpack real scenarios, like how rising interest rates amplify risks for negatively geared properties or how Gladstone’s low vacancy rate (2.1% in the June quarter 2026, according to Opteon) supports cashflow reliability. Discover data-driven tactics to optimize returns in Queensland’s dynamic investment landscape.
- Update, 14 October 2026: negative gearing is changing
- Understanding the two core investment strategies
- Negative Gearing vs Positive Cashflow: A Side-By-Side Comparison
- The Queensland Context: What Investors Need to Know
- Which Strategy Is Right for Your Financial Goals?
- Before you invest: stress-testing your chosen strategy
- How to get started with property investment in Gladstone
Understanding the two core investment strategies
Queensland property investors often choose between two main strategies: negative gearing or positive cashflow . Each approach suits different financial goals and risk profiles. Let’s break down both options clearly.
What is negative gearing?
Negative gearing occurs when your investment property expenses exceed rental income. This includes mortgage interest costs, maintenance, and property management fees. On paper, you’re making a loss each year .
Investors use this strategy to benefit from long-term capital growth. The idea is that your property’s value will increase enough to offset yearly losses. For example, if you lose $9,000 annually but the property gains $500,000 in value over five years, that’s a strong overall return .
A key advantage, for properties held before Budget night (12 May 2026) and for new builds: you can claim these losses against other income sources like your salary. This reduces your taxable income. If you’re in the 33% tax bracket and claim $9,000 in losses, you’ll save $3,000 in taxes. Just remember, you must have other income to cover the out-of-pocket loss each year.
What is positive cashflow?
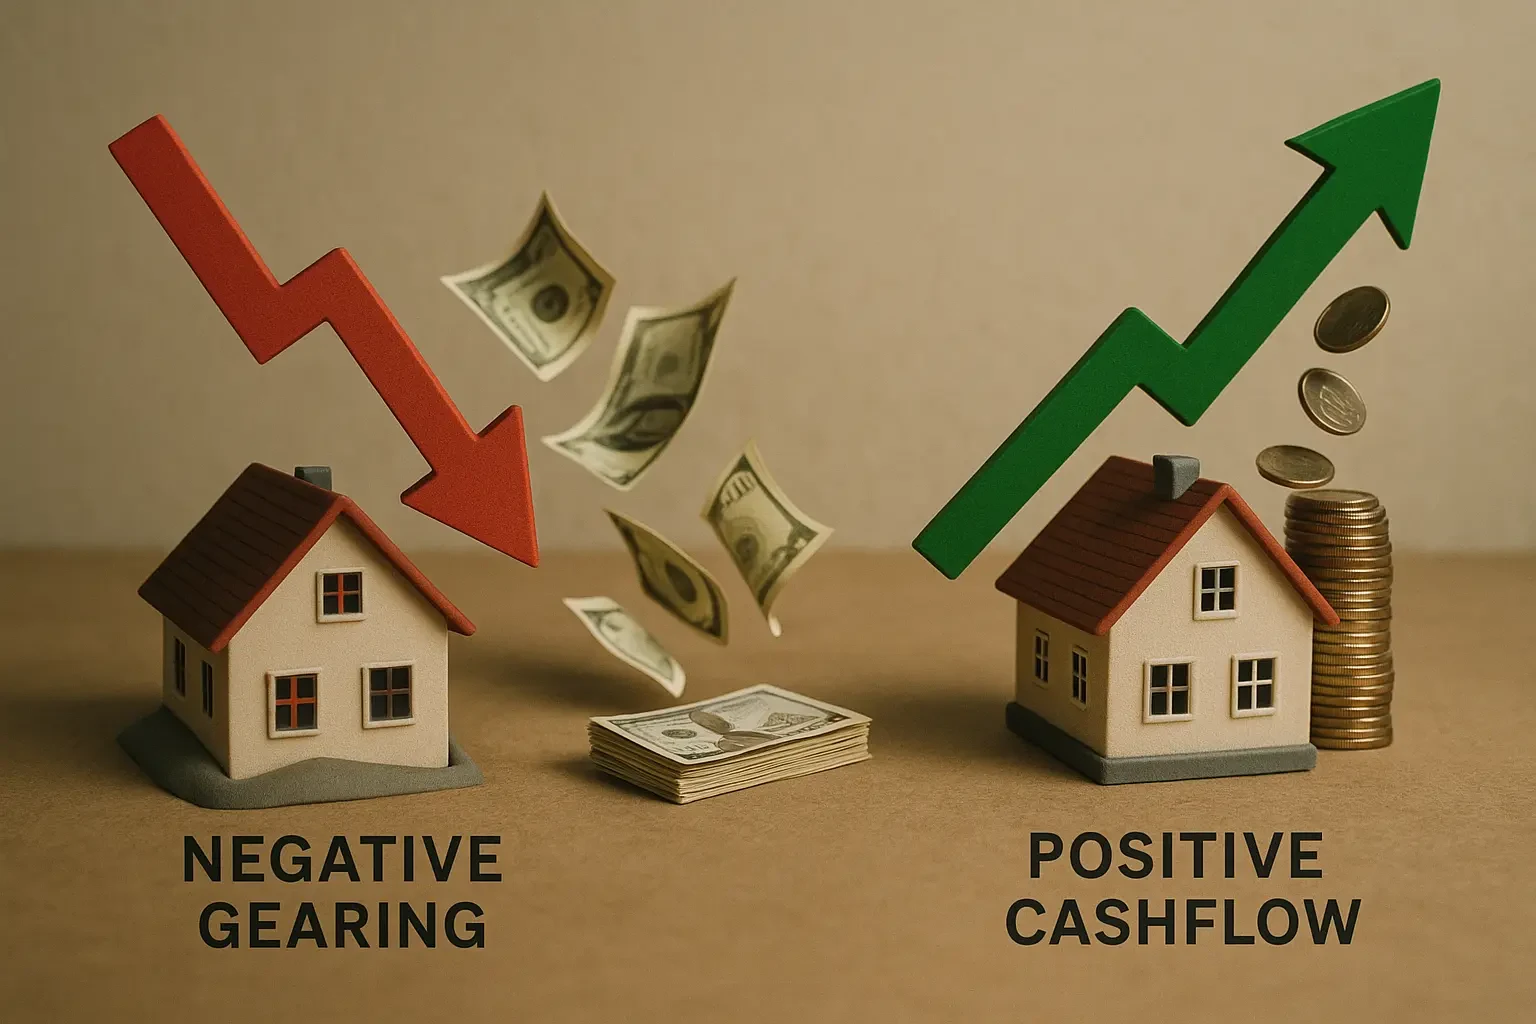
Positive cashflow works oppositely, your rental income covers all property costs and leaves extra money each month. This happens when you secure high rental returns relative to your expenses.
This creates immediate financial benefits. The extra income could accelerate mortgage repayment, fund future property purchases, or cover personal expenses. Imagine receiving $1,000 extra monthly from a Gladstone investment property, that’s $12,000 annual cash boost.
The downside? This additional income gets taxed at your regular rate. However, you’ll enjoy better cashflow security. A property with 7.05% gross yield means your rental income covers costs with room to spare . This strategy works well in areas with strong tenant demand like Rockhampton or Townsville.
- Negative gearing: Short-term loss, long-term capital growth focus
- Positive cashflow : Immediate income generation
- Tax treatment differs significantly between both approaches
- Choice depends on your cashflow needs and investment timeline
- Queensland’s regional markets offer opportunities for both strategies
Negative Gearing vs Positive Cashflow: A Side-By-Side Comparison
Key Differences At A Glance
Queensland investors face two core strategies. Negative gearing provides tax benefits but requires cash reserves to cover shortfalls. Positive cashflow properties offer immediate income while increasing taxable income. Your financial priorities and risk tolerance determine the approach .
The fundamental choice for a Queensland investor is between reducing your tax bill now with negative gearing, or boosting your income immediately with a positive cashflow property.
Gladstone does not have one median to plan against. Across the fifteen suburbs tracked on our Gladstone property market page, house medians run from about $462,500 in Barney Point to about $755,000 in Tannum Sands for the twelve months to September 2026, with indicative gross house yields between about 4.5% and 5.4% (realestate.com.au). Which strategy suits you depends on where in that range you buy. Borrowing costs matter as much as the yield: the Reserve Bank raised the cash rate three times in the first half of 2026 and twice more since, to 4.85% on 3 November 2026, which tightens the cashflow position on a negatively geared purchase compared with a year ago.
Worked example, hypothetical figures only: take a property bought for $440,000 and rented at $495 a week, against $26,400 of annual loan repayments. That combination leaves a shortfall, which is the deductible position. Positive cashflow needs either higher rent or less debt against the same property. The figures above are chosen to show the mechanics, not to describe a specific Gladstone property: actual medians across the tracked suburbs run from about $462,500 to about $755,000, so run your own numbers before drawing any conclusion.
The Queensland Context: What Investors Need to Know
Capital Growth vs Rental Yield in Key QLD Markets
Queensland’s property market isn’t uniform. Coastal areas like the Sunshine Coast and Brisbane often prioritize capital growth, making negative gearing more viable.
The Sunshine Coast, part of Queensland’s “Golden Arc” with Brisbane and the Gold Coast, combines infrastructure investment and lifestyle appeal. Population projections rising from 390,000 to 500,000 by 2041 fuel demand for properties where capital appreciation outpaces immediate rental income .
Gladstone tells a different story. Local industries like aluminium, the port and LNG support rental demand. For the 12 months to September 2026 realestate.com.au shows gross house yields of 5.2% in South Gladstone and 5.0% in Gladstone Central, and gross unit yields of 6.6% in both, before rates, insurance, maintenance, management and loan costs. That makes cashflow-positive properties more achievable here than where yields are lower, though it does not guarantee one. Opteon reports that new rental bonds lodged fell 35% on a year earlier, which it suggests may mean tenants are renewing rather than moving, so income gaps between tenants may be shorter.
Rental demand here is steady. With a 2.1% vacancy rate for the June quarter 2026, below the 2.6% to 3.5% the Real Estate Institute of Queensland treats as healthy, and rent increases limited to once every 12 months, Gladstone’s market suits strategies focused on consistent returns rather than speculative growth .
How Queensland’s Rental Laws Affect Your Strategy
Queensland’s Residential Tenancies Authority (RTA) rules shape cashflow predictability. For example, rent hikes can only occur once every 12 months, limiting your ability to offset rising mortgage rates in negatively geared properties. This constraint matters most in growth-focused markets like Brisbane, where investors might wait years for capital gains to justify ongoing losses.
Imagine owning a negatively geared property in Brisbane. A sudden interest rate rise might force you to absorb costs for over a year before adjusting rents. In Gladstone, where yields are higher, this risk is less severe, positive cashflow properties buffer against rate fluctuations. Even in Brisbane’s top-yielding suburbs like Brassall (9.9% for apartments), rent controls mean you can’t chase market rates without long-term planning.
Always factor in RTA guidelines when projecting income. Whether you choose negative gearing or positive cashflow, understanding these rules ensures your strategy aligns with local realities.
Feeling unsure which path is right for you? Let’s talk it through.
Contact us for a free, no-obligation chat about your investment goals in Gladstone
Which Strategy Is Right for Your Financial Goals?
Choosing between negative gearing and positive cashflow strategies depends on your financial situation, risk tolerance, and long-term objectives. In Queensland’s dynamic property market, factors like rising interest rates, regional growth patterns, and tax implications play critical roles.
Let’s explore which approach might suit your investment journey , whether you’re targeting Brisbane’s growing suburbs or regional hotspots like Gladstone.
When Negative Gearing Could Be a Good Fit
Negative gearing works well for investors in higher tax brackets looking to reduce taxable income while focusing on long-term capital growth . This strategy suits those with:
- Higher income and significant tax benefits from deductions
- Stable personal finances to cover annual property shortfalls
- Primary goal of long-term capital appreciation rather than immediate income
- Long investment horizon (10+ years) to weather market cycles
For example, a Brisbane investor purchasing a $700,000 property with a 20% deposit might pay $3,200/month in mortgage repayments but collect $2,500/month in rent. While covering a $8,400 annual shortfall, they could deduct these losses from a $120,000 salary, reducing tax by $2,800 annually.
Over time, if the property appreciates at Queensland’s average 5% yearly growth, the capital gain would likely outweigh short-term losses .
When Positive Cashflow Might Be the Better Choice
Positive cashflow properties provide immediate financial benefits and suit investors seeking consistent returns or with lower risk tolerance. This strategy works for those who:
- Want instant additional income to supplement their earnings
- Prefer financial self-sufficiency without relying on personal funds
- Plan to reinvest profits to accelerate debt reduction or future investments
- Target regional Queensland areas with strong rental demand and yields
In mining towns like Moranbah, a $450,000 investment might generate $500/week in rent versus $350/week in total expenses, creating $150/week in positive cashflow . This $7,800 annual income could fund retirement savings or a second property deposit. Coastal towns like Yeppoon offer similar opportunities, with 5.8% average rental yields outperforming Brisbane’s 3.2%, according to 2024 CoreLogic data.
“A successful investment property should be a sound financial decision even without the tax benefits. Gearing should be a strategic choice, not the sole reason for buying.”
Before you invest: stress-testing your chosen strategy
Investing in property requires careful planning. Whether you’re eyeing negative gearing or positive cashflow, stress-testing your strategy ensures you’re prepared for unexpected challenges . Let’s break down the key factors to consider.
Modelling for interest rate changes
Interest rates are a critical variable affecting property investments. A 1-2% rate hike can turn a slightly positive cashflow property into a loss-making one. Always test your numbers: what happens if rates rise by 1%? Can your budget absorb higher repayments? Think of this as a “ financial stress test ” for your investment.
For example, a $500,000 investment property in Brisbane with a variable rate loan could see repayments jump by $500/month under a 2% rate increase. The type of loan you choose, such as an interest-only or principal and interest loan , will also significantly impact your cash flow under rising rates.
Even a small increase could strain your budget , especially if you’re relying on rental income to cover costs.
Planning for vacancies and unexpected costs
Rental income isn’t guaranteed. Properties typically sit vacant for 2-4 weeks annually, reducing potential earnings. Always budget for these gaps to avoid cashflow surprises. In Queensland’s regional markets like Gladstone or the Sunshine Coast, vacancy rates can fluctuate seasonally due to mining cycles or tourism patterns.
- Vacancy Rate : Factor in at least 2-4 weeks of no rental income per year.
- Interest Rate Buffer : Calculate repayments with an interest rate 2% higher than the current rate.
- Maintenance Fund : Set aside 1-2% of the property’s value annually for repairs and upkeep.
- Insurance & Levies : Review if you can still cover costs if insurance premiums or council rates increase.
Unplanned expenses like emergency repairs (plumbing, aircon) or rising strata fees can derail budgets. For instance, a burst pipe in a Gladstone rental could cost $2,500 in emergency repairs.
Regular maintenance and a dedicated emergency fund help mitigate these risks while protecting your long-term returns. Remember: a 1-2% annual maintenance fund covers both routine costs and unexpected surprises, ensuring your investment stays resilient .
How to get started with property investment in Gladstone
Finding the right loan for your strategy
Choosing between negative gearing and positive cashflow strategies starts with finding the right investment loan . Your loan structure will directly impact your cashflow, tax position, and long-term returns .
For investors targeting negative gearing, look for loans with flexible repayment options and the ability to claim tax deductions. Those pursuing positive cashflow properties should prioritise lower interest rates and features that support consistent income. Understanding your borrowing capacity will clarify how much you can invest while maintaining financial stability.
A local mortgage broker can help you navigate these choices. They’ll consider Gladstone’s property market trends, current interest rates, and your personal financial situation to find a loan that supports your investment goals .
Let’s build your investment plan together
Property investment in Gladstone offers two clear paths : using short-term tax benefits with negative gearing, or generating immediate income through positive cashflow properties. Both approaches can work in Queensland’s growing property market, but they suit different investor profiles.
At AJ Home Loans Gladstone, we help local families make confident investment decisions . Whether you’re buying your first investment property or expanding your portfolio, we’ll explain how each strategy works in practice and what it means for your finances.
This information is general in nature and does not constitute financial advice . Please consult with a professional financial advisor or accountant to discuss your personal circumstances.
Conclusion Choosing between negative gearing and positive cashflow depends on your financial goals, risk tolerance, and Gladstone’s market . Negative gearing targets long-term growth with tax perks ; positive cashflow offers immediate income.
Align your strategy with local trends and personal circumstances . Ready to decide ? Partner with AJ Home Loans Gladstone to create your ideal investment strategy .
FAQ
What are the key differences between negative gearing and positive cashflow?
Negative gearing occurs when property expenses exceed rental income, creating an annual shortfall that can be claimed against taxable income to reduce tax bills . Positive cashflow happens when rental income surpasses costs, generating immediate profit . The first strategy prioritizes long-term capital growth despite short-term losses , while the second focuses on creating passive income. For example, a Gladstone property with a $430/week rent and $350/week expenses (after tax benefits) would represent positive cashflow, whereas a property with $400 rent and $500/month costs (before tax deductions) would be negatively geared.
How do tax implications differ for these strategies?
Negative gearing allows investors to deduct annual losses from their taxable income, although from 1 July 2027 an established home bought after Budget night can only offset its losses against residential property income. Worked example, hypothetical figures only: on a $9,000 yearly shortfall, an investor on a 33% marginal rate would reduce their taxable income by $9,000, and the tax effect of that depends entirely on their own rate and circumstances. Positive cashflow works the other way: a $12,000 annual profit is added to your taxable income. These are illustrations, not a projection of your outcome, and the tax treatment of either is a question for your accountant rather than your broker.
Which strategy works better in Gladstone’s property market?
On realestate.com.au’s figures for the 12 months to September 2026, Gladstone gross house yields run from about 4.5% to 5.4% and unit yields from about 5.4% to 6.8%. Gross yield is before rates, insurance, maintenance, management and loan costs, so a property can still be negatively geared once interest and costs are counted. Growth was uneven: house medians rose between 3.6% and 15.5% across the suburbs we track, and neither figure is a forecast. Investors who rely on capital growth to justify a shortfall need the cash reserves to carry it, and from 1 July 2027 an established home bought after Budget night no longer lets you offset that shortfall against your salary.
Can both strategies work together?
Yes, though rarely simultaneously in the same property . A positive cashflow property might transition to negative gearing if interest rates rise significantly. Conversely, some investors strategically use negative gearing during construction phases before shifting to positive cashflow once rental income increases. For example, a Gladstone investor might buy a $350k property with $430/week rent ($22,360/year) and $20k in annual costs, creating immediate $2,360 positive cashflow before tax considerations.
What risks should investors consider?
Negative gearing exposes investors to interest rate fluctuations, a 2% rate increase could turn a $200/month shortfall into $400/month. Positive cashflow properties face vacancy risks; Gladstone’s vacancy rate was 2.1% in the June quarter 2026, still tight, but investors should budget 2-4 weeks annual vacancy. Both strategies require careful loan selection, interest-only loans might suit negative gearing while principal-and-interest works better for positive cashflow. Always stress-test investments using 2% higher rates and 4 weeks vacancy.